🤝 Top Collaborators
🤓 Latest Submissions
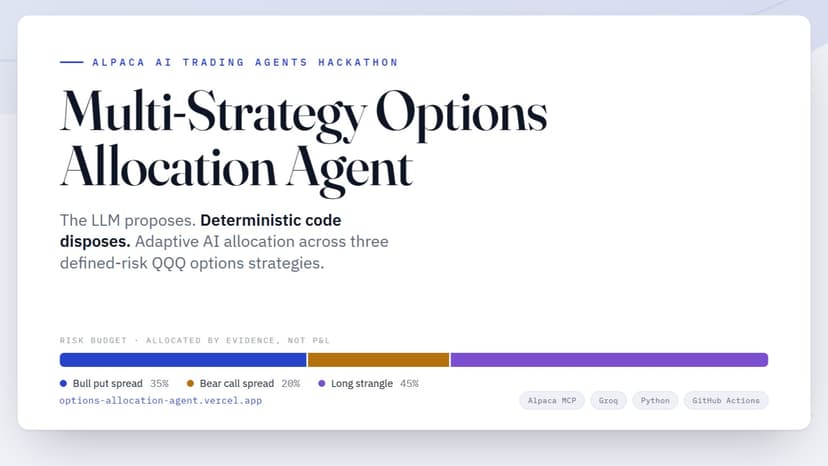
options-allocation-agent
This is an autonomous, multi-strategy options-allocation agent built on Alpaca. Instead of predicting market direction, it runs three defined-risk QQQ options strategies side by side — a bull put spread, a bear call spread, and a long strangle — and treats the real problem as capital allocation: how much of a fixed max-loss risk budget should each strategy get right now? Every cycle, the agent assembles an evidence packet from live market data: spot, EWMA realized volatility, IV percentile from VXN, and a Black-Scholes revaluation-based correlation matrix. An LLM allocator reads that evidence and proposes a total target weight for each strategy. A second LLM — the challenger — critiques the proposal against each strategy's stated thesis and invalidation conditions and returns APPROVE, MODIFY, or REJECT. The proposal then passes through deterministic, hard-coded risk gates (budget caps, per-strategy floors, buying-power checks) that can clip or veto anything the models suggest. Only then does the agent size positions to max loss and execute atomically through the official Alpaca MCP server. The design principle is "the LLM proposes, deterministic code disposes": models supply judgment and narrative, but no model output can breach a risk limit. The headline metric isn't raw P&L — it's the allocation delta: does adaptive AI allocation beat equal-weighting the same three strategies? The agent runs unattended on GitHub Actions (a free scheduled deployment) at 10:00 and 14:00 ET, persists state across runs, and publishes a live dashboard on Vercel. It ships with 306 offline tests covering the risk gates, sizing, execution, and the decision loop.
4 Sep 2026
