🤓 Latest Submissions
Portfolio Risk Guardian
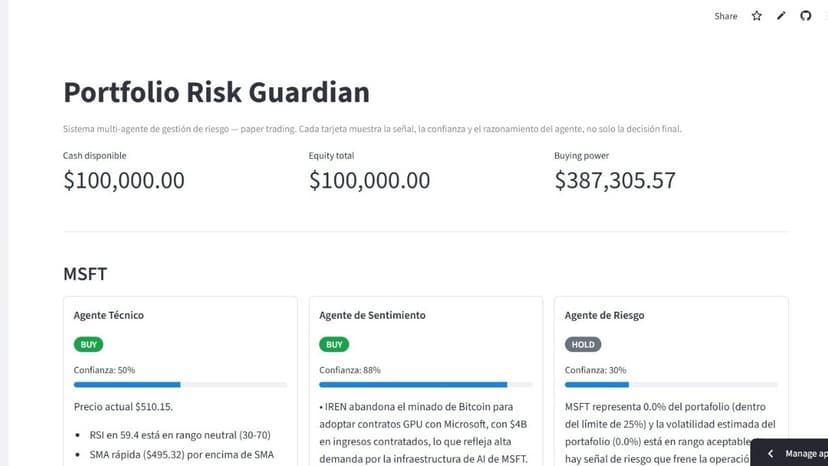
Portfolio Risk Guardian is a multi-agent trading system built on the Alpaca Trading API. Four independent agents — Technical, Sentiment, Risk, and an Orchestrator — each vote on a ticker from a different angle, explain their reasoning in natural language, and only execute a paper trade when there's clear consensus. A live Streamlit dashboard shows every agent's reasoning, not just a buy/sell signal. What sets this project apart isn't the agent count — it's the validation discipline behind it. The Technical Agent's first backtest (RSI + SMA crossover) lost money on all three tested tickers. Instead of tuning until the numbers looked good, we researched what serious quant systems actually do, applied an ADX trend filter and removed short positions, and re-measured: results improved materially (e.g. TSLA: -43% → +15.8%). Then we stress-tested that improvement instead of taking it at face value. An ADX sensitivity sweep and an out-of-universe test on 13 new tickers showed the "fix" barely generalized (avg Sharpe ≈0.06). A walk-forward validation — re-optimizing on rolling windows without look-ahead — confirmed it: out-of-sample results collapsed versus the in-sample backtest. Root cause: Grinold's Fundamental Law of Active Management — risk-adjusted performance scales with the number of independent bets, not just signal quality. A single-ticker rule is structurally the worst position to show a robust edge. Diversifying across 16 tickers with volatility-based sizing raised Sharpe from ~0.06 to 0.49. Cross-sectional momentum, a strategy shape with real academic support, reached a walk-forward Sharpe of ~0.68-0.69 — the most promising result in the project.
4 Sep 2026
